Licking County Multifamily Sales Report – July 2026
1. Executive Summary
Licking County recorded 10 multifamily property transfers during July 2026. Three qualified as Auditor-designated valid sales, producing total valid sale volume of $565,000. Activity returned after June recorded no valid multifamily sales, but July volume was concentrated entirely in small residential multifamily assets.
- 3 valid sales from 10 total multifamily transfers.
- Valid sale volume: $565,000.
- Two valid duplex sales and one valid triplex sale.
- Highest valid sale: 91 Buena Vista St Newark, Oh 43055 at $243,000.
- Lowest valid sale: 167 Essex St Newark, Oh 43055 at $137,000.
- All three valid transactions were located in Newark.
SCRE Market Position: July reflects selective liquidity rather than broad transaction depth. Small residential multifamily assets traded, while the commercial segment remained inactive on a valid-sale basis. Underwriting should remain asset-specific, debt-cost aware, and conservative on near-term rent growth.
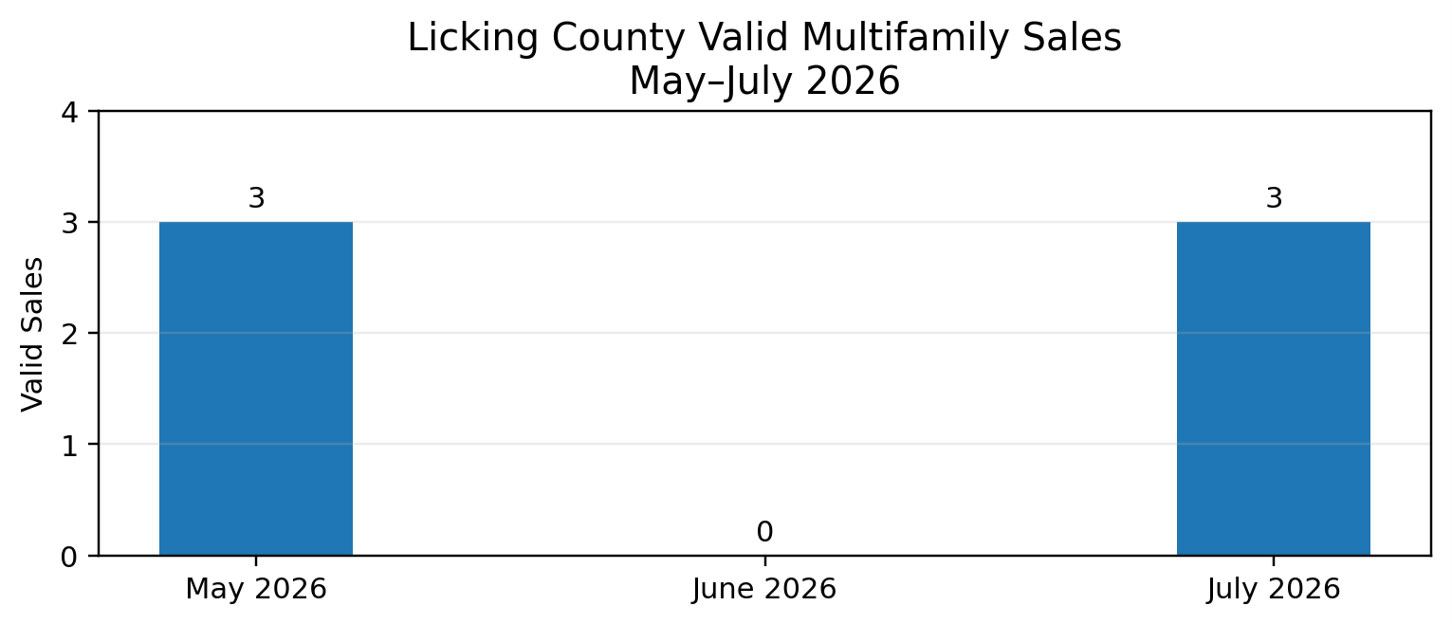
Auditor-designated valid multifamily transactions; multi-parcel transactions counted once.
2. Licking County Multifamily Sales Activity
|
Metric |
July 2026 Result |
Total multifamily transfers |
10 |
Valid multifamily sales |
3 |
Non-valid multifamily transfers |
7 |
Total valid sale volume |
$565,000 |
Average valid sale |
$188,333 |
All-property valid-sale rows |
176 |
All-property valid-sale volume |
$141,260,784 |
Method note: The “July ALL SALES” export was used only for countywide context. The multifamily analysis is based on the separate Auditor categories.
Residential Multifamily (2–4 Units)
Residential multifamily accounted for nine of July’s ten multifamily transfers and all three valid sales. The valid set included two duplexes and one triplex, all in Newark. The combined residential valid-sale volume was $565,000.
- 62 Mill Street, Newark — valid duplex sale at $185,000.
- 167 Essex Street, Newark — valid duplex sale at $137,000.
- 91 Buena Vista Street, Newark — valid triplex sale at $243,000.
Five additional duplex transfers were marked non-valid, including zero-dollar exempt conveyances and two positive-price transfers that the Auditor did not designate as valid sales. Those transactions should not be used as sale comparables without independent verification.
Commercial Multifamily (5+ Units)
The July 4–19-unit export contained one transfer: 95 South 24th Street, Newark, reported at $337,500. The Auditor marked the transfer non-valid; accordingly, it is excluded from valid transaction count, volume, average price, and sale-comparable analysis.
The absence of a valid 5+ unit trade reinforces the limited depth of the current local investment-sale market and leaves the month’s pricing evidence concentrated in duplex and triplex assets.
Highest & Lowest Valid Sale
Highest valid sale: 91 Buena Vista Street, Newark — $243,000. The property is classified as a three-family unplatted parcel and represented 43% of July valid multifamily sale volume.
Lowest valid sale: 167 Essex Street, Newark — $137,000. The sale was a two-family platted lot transaction and provides the lower bound of July’s valid multifamily pricing set.
3. Columbus MSA
The latest available Columbus research continues to describe a market with positive demand but limited pricing power. Matthews reported Q1 2026 average asking rent of approximately $1,400 per unit, annual rent growth of 0.7%, vacancy of 10.2%, and positive net absorption. Colliers similarly reported slightly positive year-over-year rent growth while the market continued to absorb recent record deliveries.
For Licking County, the implication remains balanced: regional employment and population growth support long-term apartment demand, but owners and buyers should not underwrite aggressive rent increases while newer Columbus-area supply continues through lease-up. Smaller, stabilized local assets may face less direct competition than large new communities, but operating expense and financing pressure remain material.
Ohio’s relative affordability continues to support the broader Midwest investment thesis. At the same time, statewide development feasibility remains sensitive to construction costs, financing terms, and the availability of public or tax-credit support for affordable and senior housing.
4. Capital Markets Overlay
The Federal Reserve held the federal funds target range at 3.50%–3.75% at its late-July meeting. Freddie Mac reported the average 30-year mortgage rate at 6.58% on July 23, and the bank prime rate was 6.75% at month-end. Although residential mortgage pricing is not a direct proxy for multifamily debt, the direction confirms that borrowing costs remained elevated and volatile entering August.
- Capital is available, but proceeds and pricing remain constrained by debt-service coverage requirements.
- Small multifamily deals may still transact when basis, condition, and in-place income support conservative financing.
- Commercial multifamily sellers should expect buyers to remain disciplined on cap rate, reserves, deferred maintenance, and achievable rent growth.
5. Local Development / Forward Watch List – August 2026
- Trailhead Vista, Newark: Monitor lease-up pace, asking rents, and concessions at the 308-unit West Main Street/Thornwood Drive community.
- Heath Hills / Granville Schools: M/I Homes withdrew their development plan.
- Central Park, Heath: Monitor infrastructure progress and the planned affordable assisted-living component.
- Newark small-multifamily inventory: Watch whether July’s return of duplex/triplex sales continues into August.
- Commercial multifamily liquidity: Watch for a valid 5+ unit sale that can re-establish local pricing evidence.
- Johnstown–New Albany corridor: Continue monitoring housing demand and infrastructure timing tied to regional employment growth.
Selected Market Commentary & References
“Renter demand is intact, but not strong enough to fully offset the scale of new inventory.” — Matthews Real Estate Investment Services, Columbus Q1 2026 Multifamily Market Report.
Colliers reported that Columbus rent growth remained slightly positive while the market absorbed consecutive years of record deliveries.
Freddie Mac reported a 6.58% average 30-year fixed mortgage rate as of July 23, 2026.
References: Licking County Auditor July 2026 transfer exports supplied to SCRE; Matthews Real Estate Investment Services, Columbus Q1 2026 Multifamily Market Report; Colliers, Columbus Multifamily Market Report Q1 2026; Federal Reserve selected interest-rate releases and July 2026 policy decision; Freddie Mac Primary Mortgage Market Survey; Ohio Housing Finance Agency; Vista Residential Partners project information for Trailhead Vista.